

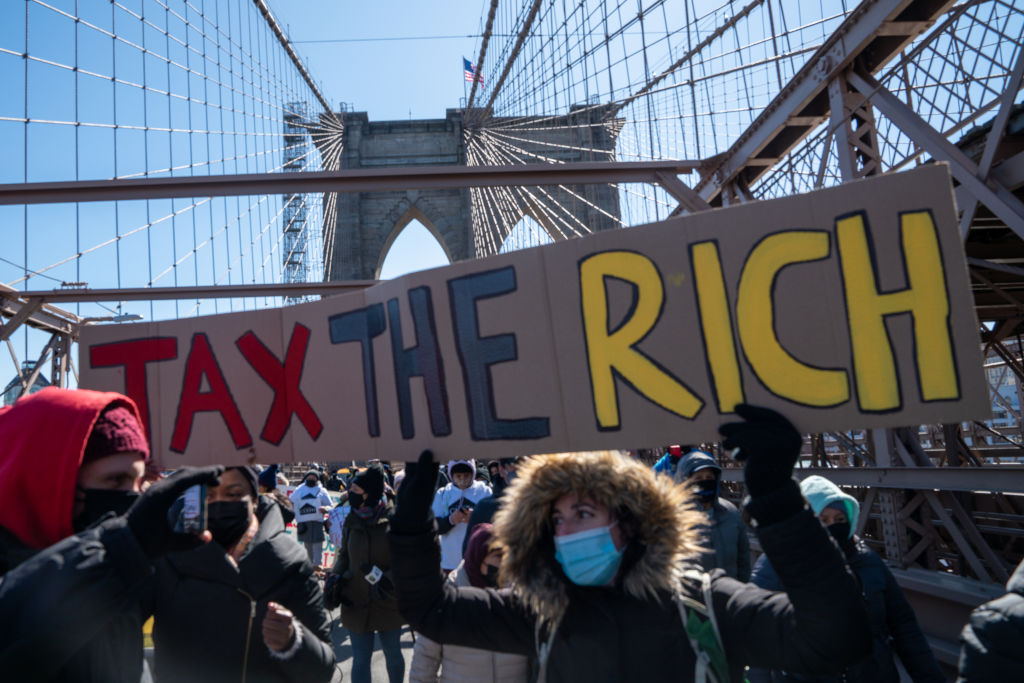
What Does It Mean to “Tax the Rich”?: Five Tax Policy Approaches Explained
November 16, 2026
By Noa Rosinplotz
Key Takeaways
- Taxing the rich is necessary for a healthy democracy. There is no one “best” method, and doing so effectively requires a range of complementary interventions.
- Because the vast majority of concentrated wealth is not taxed as ordinary income, other approaches—capital gains tax reform, alternative minimum taxes, reforms to close loopholes, and wealth taxes—should accompany income tax reforms.
Introduction: Democracy Requires Taxing the Rich
Calls to “tax the rich” are not new. But as wealth concentration reaches dizzying heights, state and federal policymakers have responded with a slate of new proposals for getting it done.
It’s not a moment too soon. Today, the top 0.1 percent hold $1 in every $6 of private wealth. Yet the very richest Americans pay an average effective tax rate of only around 24 percent, compared to 30 percent for the rest of the population—on top of vast amounts of wealth that they can pass down to their heirs tax-free. This imbalance threatens democracy from every direction.
The rise of concentrated wealth is both a cause and a consequence of the rising political power of the ultra-wealthy. Without meaningful limitations on political spending or media consolidation, the ultra-wealthy are able to convert their money directly into power and further consolidate their hold on our economic and democratic institutions.
The brief doesn’t identify one best method for taxing the rich, because in the real world there is no single best method.
There is a second vicious cycle at play when we fail to tax the rich. In September, 81 percent of survey respondents said that “a system where wealthy people and corporations pay their fair share is important to a strong and healthy democracy.” That is not the system we have. Instead, the wealthy and corporations pay far less than they should, reducing revenue for much-needed government services. Government’s failures further erode trust and faith that the government can do its job. And when people feel the system is rigged—because it is—their faith in our democracy declines even further.
Luckily, policymakers have a number of options to rebalance the scales. There are as many ways to tax the rich as there are reasons to do so, and existing tax-the-rich plans range from income tax increases on those making million-dollar salaries to wealth taxes on billionaires.
The brief doesn’t identify one best method for taxing the rich, because in the real world there is no single best method. Most of the options described here are compatible with and complementary to one another, though some are more effective than others at achieving particular goals like raising revenue or targeting concentrated wealth. Effectively taxing the rich will require a concerted and systemic effort to regain control over a tax code that the ultra-wealthy have spent decades shaping in their favor, at the federal, state, and local levels. Understanding what different tax proposals entail, and the problems they best target, is crucial to this rebalancing effort.
Major Tax Types
The following list focuses on taxation of individuals and households, and covers the categories into which many major, recent tax-the-rich proposals in current policy discussions fall. A more comprehensive list of tax reforms that would better tax our full system of wealth accumulation could also include financial transaction taxes, corporate tax increases, progressive property tax increases, and reforms to the taxation of trusts, among other options.
More Progressive Income Taxes
The US has had some form of progressive income tax since 1916. People who earn most of their income from labor pay that tax as a matter of course, and most salaried workers have their income tax deducted directly from their paycheck, making any needed adjustments once a year during tax season.
The highest marginal tax rate on wage income in the US is now 37 percent. However, as Roosevelt Fellow Samarth Gupta wrote in his September 2026 brief, for much of the 20th century the top rate was over 50 percent, rising to 94 percent for the very highest earners under Franklin D. Roosevelt’s “confiscatory” taxes during World War II. Today’s fewer and smaller tax brackets mean that the uber-rich, very rich, and rich all face the same marginal tax rate: the top 0.01 percent of filers, who in 2023 made at least $16 million, and the top 1 percent of filers, who made around $700,000, fell into the same bracket. Gupta recommends adding seven new brackets, with a top rate of either 50 or 70 percent, following work from Thomas Piketty, Emmanuel Saez, and Stefanie Stantcheva that estimated revenue-maximizing top rates of between 57 and 83 percent, depending on the potential responses of top earners. Clearly, there is both room and precedent for more and higher tax brackets.
Raising top income tax rates is a simple solution. It doesn’t require any new systems of valuation, it’s unlikely to be seriously challenged in court, and the US has done it before. As such, it could raise a lot of revenue without implementation delays and address serious vertical inequities within tax brackets.
To target the very wealthiest, however, raising income tax rates is a less effective tool. At the highest levels of wealth, relatively little income is ever subject to the individual income tax, which primarily targets ordinary wages. Higher income taxes would best target top earners: surgeons with million-dollar paychecks, not start-up founders with billions of dollars in the bank or in the markets.
Mark-to-Market Taxes and Capital Gains Tax Reform
Most people live off the ordinary wage income that is subject to the income tax, which is taxed every paycheck as it is earned. The ultra-wealthy, however, don’t earn most of their income as wages. Instead, they earn it as returns on their investments. These returns aren’t taxed until they are sold or transferred, allowing them to accrue enormous amounts of value over time. For the very wealthiest, who have enough money that they don’t need to sell assets to pay for their day-to-day life, the ability to delay realization means wealth can grow nearly unchecked. And when (or if) those returns are taxed, they get a discount: The long-term capital gains tax rate caps out at 20 percent, just over half of the maximum rate for ordinary income. This preferential rate overwhelmingly benefits the wealthy: In 2022, over 70 percent of the benefit went to taxpayers with income above $1 million.
The differential treatment of wage and capital income means that the wealthiest are taxed on only a fraction of their economic income—defined here as taxed income plus new unrealized gains—a more accurate barometer of a person’s ability to buy things than their taxable income alone.1 The current tax base includes 98 percent of economic income for the bottom half of the population by wealth. For the 50–90th percentiles, that share is 87 percent. However, only about 60 percent of economic income is included in the current tax base for the top 1 percent of wealth-holders, and only about half is included for the top 0.1 percent and the Forbes 400. Because the wealthy are also more likely to have realized capital gains instead of wages, they are taxed on both a smaller share of their economic income and at a lower rate.
Some proposals, therefore, seek to reform the taxation of capital gains so that investment income is taxed more like wage income. Mark-to-market (MTM) taxation would impose a tax on the yearly increase in value of a person’s (or household’s) assets, as though they had been sold: thereby taxing the assetholder’s income as it accrues just like the income of a teacher who receives biweekly paychecks. Most MTM tax-the-rich proposals would set a wealth threshold, exempting those with less than a certain amount of lifetime investment gains. Among other considerations, an MTM system would have to account for years when losses exceed gains. This could be accomplished, for instance, by allowing losses to carry forward to subsequent-year tax bills. MTM taxes have an economic efficiency benefit on top of equity benefits: By eliminating the incentive to hold investments to avoid incurring taxes, they encourage investors to better allocate capital to firms that need to grow and hire.
In addition, equalizing the tax rates on wage and capital income would further reduce the tax advantage that people who earn their income from investments hold over people who earn their income from labor. Capital income that is currently taxed at a maximum of 20 percent (or 23.8 percent, when including the Net Investment Income Tax) would instead be subject to the same tax schedule as ordinary income, with a maximum rate of 37 percent (or higher, if income tax brackets were reformed at the same time).
Alternative Minimum Taxes
Alternative minimum taxes (AMTs) are already part of the tax code, for both individuals and corporations. The individual AMT requires those with income above a certain threshold (around $90,000 for single filers in 2026) to calculate their tax liability under both the regular income tax structure and an alternative structure, and pay the higher of the two. The maximum AMT rate is lower than the regular rate, but the AMT limits deductions and credits, often resulting in a higher effective tax rate. In essence, the AMT is supposed to act as a backstop by ensuring that no amount in deductions prevents a high-income taxpayer from paying a reasonable amount in income tax.
While the idea of an AMT is relatively simple, the execution is less so. The existing individual AMT has a history of complexity and has at times failed to effectively target high-income taxpayers when brackets were not adjusted for inflation.
Some tax-the-rich proposals would apply new, higher AMTs to those above a certain threshold of income, or apply an AMT that includes (currently untaxed) unrealized gains. In 2011, Warren Buffett popularized the term “Buffett Rule” after noticing that he paid a lower federal tax rate than his secretary. President Barack Obama adopted the term a year later to refer to a proposal for an AMT that would ensure anyone making over $1 million a year have an effective tax rate on realized income of at least 30 percent, around what middle-class families pay on average.
AMTs have the advantage of ensuring some degree of fairness by setting a floor on effective tax rates. An AMT indexed to the average middle-class tax rate is hardly radical, even as a floor—a progressive tax code would surely ask Warren Buffett, the ninth richest person in the world, to pay a higher effective tax rate than his secretary.
AMTs can, however, serve as a foundation to achieve much more progressive taxation, particularly when coupled with other tax changes discussed here. In particular, if applied to unrealized gains, an AMT would likely represent a large tax increase for some wealthy taxpayers, given that the current minimum tax rate on unrealized gains is zero.
“Closing Loopholes” Reforms
Rather than impose higher taxes directly on the rich, certain reforms would close the loopholes that the rich use to lower their tax rates. There are many such potential reforms, as there are many loopholes, but a few major ones are highlighted here.
Some reforms would disincentivize the “buy, borrow, die” and “buy, save, die” strategies that allow the rich to accumulate wealth, save most of it, borrow against it when they need to spend large amounts, and then pass it along to their heirs tax-free. Taxes may be semi-optional for the ultra-wealthy, but (despite their best efforts) death is not. At the moment, when a person dies while holding unrealized gains that weren’t taxed in their lifetime, those gains are wiped out for tax purposes for their heirs. The stepped-up basis loophole overwhelmingly benefits the ultra-wealthy, allowing them to benefit not only from the preferential tax rate on capital gains but, if they can avoid selling their assets for long enough, from no tax rate at all.
Taxing loans and lines of credit for those with a very high income or net worth could also, in theory, force the wealthy to realize the capital gains they want to spend (and therefore pay taxes on them) rather than borrowing against them. However, Zachary Liscow and Edward Fox have found that these loans make up only about 1–2 percent of economic income for the ultrarich, given that they usually also have enough liquid, taxable income to fund their daily lives.
The estate tax is also riddled with loopholes, and its ludicrously high exemption threshold allows many large estates to escape taxation without even needing to use them. At the moment, only estates valued at over $15 million per person (or $30 million for a married couple) are subject to the estate tax. Lowering the exemption threshold, therefore, would be one way to allow the estate tax to reach the large estates it is designed to tax. Another would be to eliminate the estate and gift taxes altogether and instead impose an inheritance tax on those who inherit large estates. Taxing inheritances as (or at greater rates than) ordinary income would address the inequitable tax benefit that inherited income receives over earned income. This approach would also reward those who distribute their estates among greater numbers of inheritors, further reducing wealth concentration.
Preferential rates for pass-through business income, among other forms of income, encourage those who can afford it to pay for canny tax advisors to game the tax code as much as possible, redirecting income through whatever stream is taxed at the lowest rate. The carried interest loophole, for example, allows general partners in investment funds to apply the long-term capital gains rate, rather than the much higher ordinary income tax rate, to much of their income. Equalizing rates across all forms of income would disincentivize some forms of gaming the system, promote fairness, and raise revenues.
Wealth/Net Worth Taxes
Though the term “wealth tax” is often used broadly to refer to any tax that targets the wealthy, a true wealth tax is generally understood to be a tax on net worth for those above a certain wealth threshold. In addition to more effectively taxing income, taxing accumulated wealth directly—independently or in concert with other tax reforms discussed above—is an increasingly popular approach. Most proposals would tax all of an individual’s personal and business wealth, realized and unrealized: shares in companies, stock portfolios, and yachts included (sometimes with exclusions, such as for primary residence). Wealth taxes can be designed to include phase-in thresholds and periods of time over which the amount can be paid. Because a wealth tax taxes everything, if properly enforced, it eliminates any incentive to shift around income and assets.
The US does not yet impose any broad-based wealth taxes, at the state or federal level, but they aren’t a novel idea. Both the estate tax and the expatriation tax (paid by those above a certain income or wealth threshold who leave the US and renounce their US citizenship) require valuing and then taxing net worth, and property taxes at the state and local level already constitute a regular tax on a portion (for many middle-class families, a significant portion) of net worth. Spain, Norway, and Switzerland all tax wealth to varying degrees.
Wealth taxes have many detractors. Some argue that valuing net worth is so complex as to prove impossible, especially among the very wealthiest. Others point out that researchers have developed a number of strategies to value net worth and that the ultra-wealthy already do have very complicated taxes: A wealth tax would channel that complexity into paying taxes, rather than avoiding them.
Other detractors note that several countries, most recently France, have found their wealth taxes so unwieldy and ineffective that they ended up repealing them. However, these taxes were designed very differently from US wealth tax proposals, with narrower bases and lower rates. Nonetheless, international examples provide plenty of lessons for the US to learn from, particularly around setting a sufficiently high wealth threshold and ensuring that exemptions do not allow the wealthy to shift their assets around the tax.
Where and Who to Tax
Jurisdiction
Tax the rich proposals span the local, state, federal, and even international levels. Opponents of state- and local-level taxes on the rich argue that they are too easy to avoid, as taxpayers can simply move states. There is little to no evidence that this tax flight actually occurs, however. IRS data following Massachusetts’s 2023 millionaire surtax shows that high-income taxpayers have not left the state, confirming research showing that tax incentives only marginally influence migration. Personal and business ties often make moving undesirable for other reasons—not least because the job or industry that has made someone ultra-wealthy may not exist in another state.
At the federal level, tax migration is even more difficult, and tax increases on the rich can therefore be higher. Because the US has citizenship-based taxation, those who leave the country to evade a federal tax would also have to renounce their US citizenship and in doing so pay the expatriation tax.
That said, federal taxes on unrealized gains face potential Supreme Court challenges. In the landmark 2024 Moore vs. US case, the court declined to rule that taxes can only be imposed on realized income, leaving the door open to a future wealth or MTM tax, though it is unclear how the court would rule on such taxes.
Design considerations could preempt this issue. Roosevelt Senior Fellow Brian Galle’s proposal for a Fair Share Tax would reap the benefits of a tax on unrealized gains while only taxing realized income, by imposing a tax at realization equal to what would have been paid under an annual MTM tax. In a proposal that was later put forward by the Biden administration, Saez, Danny Yagan, and Gabriel Zucman designed a system of capital gains withholding, requiring wealthy taxpayers to prepay taxes on their unrealized gains over a period of time. And while the feasibility of a federal tax on unrealized gains remains in flux, states and localities can lead the charge.
The larger the jurisdiction, the harder a tax is to escape, and Zucman has even proposed an internationally coordinated 2 percent minimum tax on billionaire wealth. If properly implemented, this tax would be essentially inescapable (at least until billionaires create their own colony on Mars).
Wealth Thresholds
Proposals to tax the rich invariably have to define a threshold for “rich.” Billionaires may hold a disproportionate amount of wealth and power even among the ultra-wealthy, but there are relatively few of them. Depending on the exact measurement, there are around 1,000 billionaires in the US, and they collectively own about $9 trillion in wealth. By contrast, around 430,000 households have a net worth above $30 million, and 74,000 have a net worth above $100 million. Collectively, the top 0.1 percent—who each hold more than ~$45 million—own over $25 trillion in wealth. Taxing only billionaires would leave most of that pot untouched.
The current top income tax rate applies to individuals who make $626,351 and up (or couples who make $751,601 and up). Without reforms to the treatment of unrealized gains, taxes on those who take home over $1 million a year in income would affect only around 800,000 taxpayers, or about 0.5 percent of filers. That population excludes many ultra-wealthy individuals who don’t have ultra-large ordinary incomes: Warren Buffett, for instance, famously earned a $100,000 salary for decades while being one of the richest men in the world.
Defining a wealth threshold is also tricky. This is in part because the US doesn’t tax wealth, and because the tax code incentivizes forms of manipulation that make net worth estimation more difficult than it should be. (One advantage of wealth taxation could be more precise data on wealth distribution.)
Conclusion
The future of our democracy depends on our ability to tax the rich. But our goals in doing so should inform the methods we use: different combinations of tax type, jurisdiction, and wealth threshold have vastly different implications.
Raising the ordinary income tax for billionaires alone, for instance, is unlikely to make a dent in concentrated wealth, because billionaires generally don’t become billionaires through wage income. A minimum income tax that includes unrealized gains can raise far more revenue than one that doesn’t. And while raising ordinary income taxes may raise revenue, ordinary income taxes don’t address the formation of dynasties or the inequities inherent in a system that privileges income from stocks and inheritances over income from work. The question isn’t whether, when, or why to tax the rich, but how: a more difficult question, but one we have the tools to answer.
Footnote
- There are a number of different methodological approaches to calculating and defining economic income, but we use the definition from Edward Fox and Zachary Liscow here. ↩︎
Acknowledgments
The author would like to thank Katherine De Chant, Brian Galle, Hannah Groch-Begley, Michael Madowitz, and Kitty Richards for their feedback, insights, and contributions to this paper. Any errors, omissions, or other inaccuracies are the author’s alone.
Suggested Citation
Rosinplotz, Noa. 2026. “What Does It Mean to “Tax the Rich”?: Five Tax Policy Approaches Explained,” Roosevelt Institute, November 17.
RELATED RESOURCES
Author
Noa Rosinplotz
Senior Research AssociateAs a senior research associate at the Roosevelt Institute, Noa Rosinplotz supports think tank staff and fellows in their research.